
Insurance is the biggest scam in the country
Discussion


Warning: Massive rant incoming.
For the love of all things holy, can insurance do one thing right?
I rang up last week to ask how much my policy would increase by if I was to get an aftermarket screen in my car with apple carplay etc. Made it explicitly clear that NO work has been done to the car and this is a QUOTE. I was told by the fella that it would be an increase of £17. No biggy. A few days later, a letter comes through the door... asking for multiple pictures of the car, all of which with my license in frame, to confirm my policy details. No biggy, but unnecessary given how clear I was.
Fast forward to today, I book in with a company to supply and fit a wonderful BMW GXX chassis screen to my F31, I book the day off work and agree 12:30 with the company. I then promptly ring my insurance, refer them to my previous conversation and I'm met with: "Sorry, we don't cover upgraded screens"
Absolutely, completely, utterly and 100% dumbfounded. I am in silence for about 5 seconds thinking about the level of bo11ocks I'm listening to.
Now stuck with £500 store credit that lasts 12 months with the company. Safe to say I will be ringing around in 2 weeks time when my insurance is up for renewal.
To conclude, f king stty ttty bks stupid y wkery sthead day.
For the love of all things holy, can insurance do one thing right?
I rang up last week to ask how much my policy would increase by if I was to get an aftermarket screen in my car with apple carplay etc. Made it explicitly clear that NO work has been done to the car and this is a QUOTE. I was told by the fella that it would be an increase of £17. No biggy. A few days later, a letter comes through the door... asking for multiple pictures of the car, all of which with my license in frame, to confirm my policy details. No biggy, but unnecessary given how clear I was.
Fast forward to today, I book in with a company to supply and fit a wonderful BMW GXX chassis screen to my F31, I book the day off work and agree 12:30 with the company. I then promptly ring my insurance, refer them to my previous conversation and I'm met with: "Sorry, we don't cover upgraded screens"
Absolutely, completely, utterly and 100% dumbfounded. I am in silence for about 5 seconds thinking about the level of bo11ocks I'm listening to.
Now stuck with £500 store credit that lasts 12 months with the company. Safe to say I will be ringing around in 2 weeks time when my insurance is up for renewal.
To conclude, f
king stty ttty bks stupid y wkery sthead day.Edited by TypicalBMWDriver on Wednesday 12th February 14:10
What's mad is I've never even considered a change in insurance for changing anything audio related! So in my innocence I would have never made such a call, shame you did, maybe lol...
Does sound a stty thing to do by them though, and doesn't really make sense. I guess the key is to get everything in writing! My insurance company accepts modifications (if that's what it is) via a form online, probably the better way to go.
Does sound a s
tty thing to do by them though, and doesn't really make sense. I guess the key is to get everything in writing! My insurance company accepts modifications (if that's what it is) via a form online, probably the better way to go.Was it Hastings by any chance? There have been a lot of people getting this request to supply pictures after they bought insurance with the threat of having their policy cancelled if they didn't comply. I would recommend cancelling your policy at the earliest opportunity and getting insured elsewhere.
Also, is it possible they misunderstood your request? ie declaring a modification vs requesting cover for it (most policies don't cover mods but you can still have them on your car AFAIK).
Also, is it possible they misunderstood your request? ie declaring a modification vs requesting cover for it (most policies don't cover mods but you can still have them on your car AFAIK).
CrippsCorner said:
What's mad is I've never even considered a change in insurance for changing anything audio related! So in my innocence I would have never made such a call, shame you did, maybe lol...
Does sound a stty thing to do by them though, and doesn't really make sense. I guess the key is to get everything in writing! My insurance company accepts modifications (if that's what it is) via a form online, probably the better way to go.
Most people don't. I tried to do the good thing and go out of my way to be all "Just so that you're aware my good friend Mr. Underwriter" so that in the event of a claim, I'm all good. Backfired massively. Does sound a s
tty thing to do by them though, and doesn't really make sense. I guess the key is to get everything in writing! My insurance company accepts modifications (if that's what it is) via a form online, probably the better way to go.Yeah it's classed as a modification, I had to ring up for it though.
Neil H said:
Was it Hastings by any chance? There have been a lot of people getting this request to supply pictures after they bought insurance with the threat of having their policy cancelled if they didn't comply. I would recommend cancelling your policy at the earliest opportunity and getting insured elsewhere.
Also, is it possible they misunderstood your request? ie declaring a modification vs requesting cover for it (most policies don't cover mods but you can still have them on your car AFAIK).
It may or Also, is it possible they misunderstood your request? ie declaring a modification vs requesting cover for it (most policies don't cover mods but you can still have them on your car AFAIK).

I had exactly what you described, twice now in one year. My insurance is up for renewal in 2 weeks, so I will be shopping around.
However, I am 19 and drive a bmw 320d. It's a 2L and my insurance is a fantastic price tbf... so it might leave me with no choice but to continue with them if they offer me a price that's too good to turn down. I'm going to ring some modified car insurance companies regardless, as I wanted a quote for going stage 1

That is a really good point, the lady did say they don't offer cover for that. I'm going to get my store credit for now, and ring up when my insurance is up for renewal. Thank you for that. I don't want it covered, I just want it declared - as you said.
Dingu said:
Was it mid term when you first asked and now at point of renewal hence the possibility that the criteria have altered?
In any case I would recommend shopping at renewal regardless and if you have just made alterations being at a point you can naturally shop more easily is good.
I first rang them regarding this on the 3rd of February... 2025.In any case I would recommend shopping at renewal regardless and if you have just made alterations being at a point you can naturally shop more easily is good.
My second call was today, 12th Feb.
I consciously waited until this time of year before I started looking so that I had more flexibility, as you said.
TypicalBMWDriver said:
Warning: Massive rant incoming.
For the love of all things holy, can insurance do one thing right?
I rang up last week to ask how much my policy would increase by if I was to get an aftermarket screen in my car with apple carplay etc. Made it explicitly clear that NO work has been done to the car and this is a QUOTE. I was told by the fella that it would be an increase of £17. No biggy. A few days later, a letter comes through the door... asking for multiple pictures of the car, all of which with my license in frame, to confirm my policy details. No biggy, but unnecessary given how clear I was.
Fast forward to today, I book in with a company to supply and fit a wonderful BMW GXX chassis screen to my F31, I book the day off work and agree 12:30 with the company. I then promptly ring my insurance, refer them to my previous conversation and I'm met with: "Sorry, we don't cover upgraded screens"
Absolutely, completely, utterly and 100% dumbfounded. I am in silence for about 5 seconds thinking about the level of bo11ocks I'm listening to.
Now stuck with £500 store credit that lasts 12 months with the company. Safe to say I will be ringing around in 2 weeks time when my insurance is up for renewal.
To conclude, fking stty ttty bks stupid y wkery sthead day.
I've had issues like this, open a complaint, calls are recorded, if its not sorted satisfactorily then goto the Financial Ombudsman, I've taken this route on a couple of occasions and had things sorted very quicklyFor the love of all things holy, can insurance do one thing right?
I rang up last week to ask how much my policy would increase by if I was to get an aftermarket screen in my car with apple carplay etc. Made it explicitly clear that NO work has been done to the car and this is a QUOTE. I was told by the fella that it would be an increase of £17. No biggy. A few days later, a letter comes through the door... asking for multiple pictures of the car, all of which with my license in frame, to confirm my policy details. No biggy, but unnecessary given how clear I was.
Fast forward to today, I book in with a company to supply and fit a wonderful BMW GXX chassis screen to my F31, I book the day off work and agree 12:30 with the company. I then promptly ring my insurance, refer them to my previous conversation and I'm met with: "Sorry, we don't cover upgraded screens"
Absolutely, completely, utterly and 100% dumbfounded. I am in silence for about 5 seconds thinking about the level of bo11ocks I'm listening to.
Now stuck with £500 store credit that lasts 12 months with the company. Safe to say I will be ringing around in 2 weeks time when my insurance is up for renewal.
To conclude, f
king stty ttty bks stupid y wkery sthead day.Edited by TypicalBMWDriver on Wednesday 12th February 14:10
I think the problem is, insurance is based on "utmost good faith" and is referred to as "uberrima fides."
But, punters have long been scamming, misdeclaring, lying, having fake accidents with half the town int he car and generally seeing it as something to be exploited.
Now, the companies are not blameless and can be quite unpleasant but they end up having to protect themselves from fraud to save paying out millions to those using them as a money tree and going bust.
Insurance fraud is always seen as a victimless crime, but guess what, it isnt and now they have more tools to clamp down on people, so, people doing it correctly like the OP get treated like this.
Its like places where there is rampant shoplifting, businesses pull out and no shops left, so they think they are getting away with it but there is always a payback.
But, punters have long been scamming, misdeclaring, lying, having fake accidents with half the town int he car and generally seeing it as something to be exploited.
Now, the companies are not blameless and can be quite unpleasant but they end up having to protect themselves from fraud to save paying out millions to those using them as a money tree and going bust.
Insurance fraud is always seen as a victimless crime, but guess what, it isnt and now they have more tools to clamp down on people, so, people doing it correctly like the OP get treated like this.
Its like places where there is rampant shoplifting, businesses pull out and no shops left, so they think they are getting away with it but there is always a payback.
TypicalBMWDriver said:
Warning: Massive rant incoming.
For the love of all things holy, can insurance do one thing right?
I rang up last week to ask how much my policy would increase by if I was to get an aftermarket screen in my car with apple carplay etc. Made it explicitly clear that NO work has been done to the car and this is a QUOTE. I was told by the fella that it would be an increase of £17. No biggy. A few days later, a letter comes through the door... asking for multiple pictures of the car, all of which with my license in frame, to confirm my policy details. No biggy, but unnecessary given how clear I was.
Fast forward to today, I book in with a company to supply and fit a wonderful BMW GXX chassis screen to my F31, I book the day off work and agree 12:30 with the company. I then promptly ring my insurance, refer them to my previous conversation and I'm met with: "Sorry, we don't cover upgraded screens"
Absolutely, completely, utterly and 100% dumbfounded. I am in silence for about 5 seconds thinking about the level of bo11ocks I'm listening to.
Now stuck with £500 store credit that lasts 12 months with the company. Safe to say I will be ringing around in 2 weeks time when my insurance is up for renewal.
To conclude, fking stty ttty bks stupid y wkery sthead day.
What do you do for a living?For the love of all things holy, can insurance do one thing right?
I rang up last week to ask how much my policy would increase by if I was to get an aftermarket screen in my car with apple carplay etc. Made it explicitly clear that NO work has been done to the car and this is a QUOTE. I was told by the fella that it would be an increase of £17. No biggy. A few days later, a letter comes through the door... asking for multiple pictures of the car, all of which with my license in frame, to confirm my policy details. No biggy, but unnecessary given how clear I was.
Fast forward to today, I book in with a company to supply and fit a wonderful BMW GXX chassis screen to my F31, I book the day off work and agree 12:30 with the company. I then promptly ring my insurance, refer them to my previous conversation and I'm met with: "Sorry, we don't cover upgraded screens"
Absolutely, completely, utterly and 100% dumbfounded. I am in silence for about 5 seconds thinking about the level of bo11ocks I'm listening to.
Now stuck with £500 store credit that lasts 12 months with the company. Safe to say I will be ringing around in 2 weeks time when my insurance is up for renewal.
To conclude, f
king stty ttty bks stupid y wkery sthead day.Edited by TypicalBMWDriver on Wednesday 12th February 14:10
The Insurance industry is not defined by one motor insurer acting inconsistently. Whilst your experience is frustrating, you can vote with your feet buying a near homogeneous product in a competitive marketplace either mid term or at renewal.
Buying a hamburger for the cheapest price in the food court won't necessarily get you the best hamburger or service. You pay your money and take your choice. Whilst insurance is seen to be a product with no immediate benefit for your money as you don't receive a physical product (just a "promise" if things go wrong), that time when you write your car off or it gets stolen and they send you £20k to your bank account it won't seem like so much of a scam any more, will it?
S1MMA said:
that time when you write your car off or it gets stolen and they send you £20k to your bank account it won't seem like so much of a scam any more, will it?
OK maybe the OP shouldn't have said 'scam' as this is more just plain old incompetence, and it seems pretty indefensible really. I'd very much hope that given the events described, and in particular the short period of time between the OP checking what difference the screen would make to his policy and actually fitting the thing (or attempting to fit it), that it can be sorted via the insurer's normal complaints process. Shoddy stuff.TypicalBMWDriver said:
For the love of all things holy, can insurance do one thing right?
Yes they can. I changed insurer recently at renewal and the new insurer emailed me all the new documentation, all correct, and in good time. And my car is already on the MID database.Anyone else had their insurance do something right?
ChocolateFrog said:
I wouldn't even tell them about a different head unit.
I accept that should it get nicked (seems rare these days) or i somehow burn the car down that I'd be taking it on the chin but I'd rather that than give them a chance to refuse insurance.
Unfortunately, it’s not necessarily that simple. I accept that should it get nicked (seems rare these days) or i somehow burn the car down that I'd be taking it on the chin but I'd rather that than give them a chance to refuse insurance.
If I wasn’t a PH member, I would also take the view that an accessory or anything else I happened to have in the car and that my insurer didn’t know about would be unlikely to be insured under the car policy.
However as we have seen from numerous PH threads, it only needs your insurer to decide unilaterally that something is actually not an accessory (or a repair, replacement etc.), but a “Modification”, and they can then decide that your car itself isn’t insured. This, even if the offending item would appear to have little or nothing to do with insurance risk and is not flagged as a potential problem in any of your policy documentation.
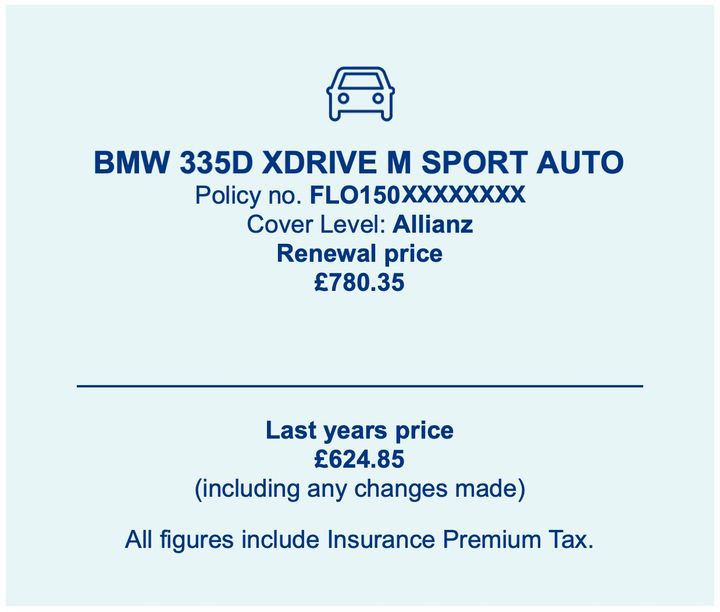
I got a quote on Monday morning to swap from my 320D to the same model 335D. Was about £150 more than the 320D, so £XXX+£150, so didn't do my usual comparison site shenanigans.
Go to see the car on Monday afternoon, decide it the one for me and the cost to change was fine as there was no quibble with the trade-in I'd been offered.
Go back online to accept the quote and it says something like "That will be £18 to change vehicles for the remainder of your policy (all of about 10 hours), and your renewal (in about 10 hours) will be £XXX+£350". WTAF!!!
Morning (20-Jan, 9:34):
Afternoon (20-Jan, 14:57):
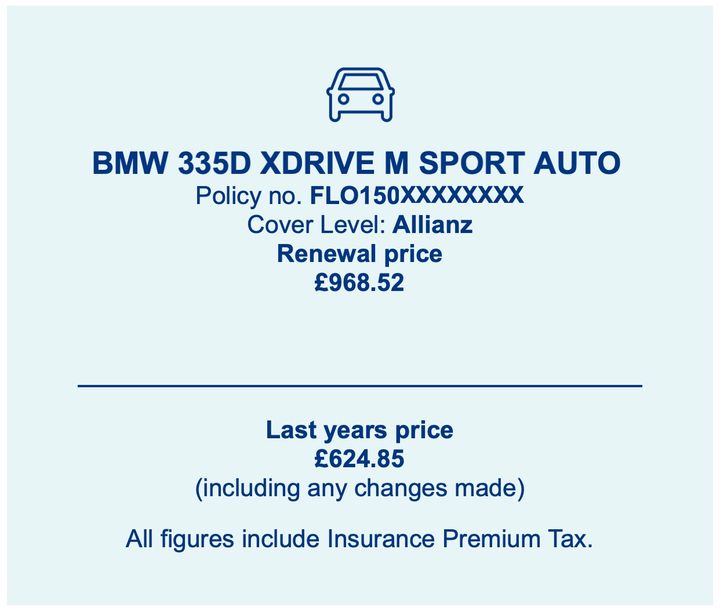
At least it forced me to do a quick comparison site check whilst I was at the dealership, and checked what it would cost to add to my multi-car policy. Eventually got the 335D down to lower than the 320D was last year (which was originally on a the multi-car policy, but the 320D part went up 60% over 2 years so I removed it).
Go to see the car on Monday afternoon, decide it the one for me and the cost to change was fine as there was no quibble with the trade-in I'd been offered.
Go back online to accept the quote and it says something like "That will be £18 to change vehicles for the remainder of your policy (all of about 10 hours), and your renewal (in about 10 hours) will be £XXX+£350". WTAF!!!
Morning (20-Jan, 9:34):
Afternoon (20-Jan, 14:57):
At least it forced me to do a quick comparison site check whilst I was at the dealership, and checked what it would cost to add to my multi-car policy. Eventually got the 335D down to lower than the 320D was last year (which was originally on a the multi-car policy, but the 320D part went up 60% over 2 years so I removed it).
Forums | General Gassing | Top of Page | What's New | My Stuff