
Am I going to be poor when I retire?
Discussion


I'm 33 soon and if I'm honest my pension is not great. I started it late due to a combination of things, but now I'm fully aware I need to get my act together.
I've got £20k in an adventurous plan, and I'm paying in over £1k each month by salary sacrifice.
What's confusing me is that I'm finding it hard to understand what my projected retirement figures will be. I know there are many assumptions to take into account, and absolutely everything is a best guess. Still, the figures I am getting are widely different (from £12k PA to £40k PA).
In any case, Nutmegs calculator lets me input my own figures, and assuming 8% growth the figures look healthy?

It's probably worth mentioning that I'd be happy with an annual income of £20k, but I have no idea what that will be in 25 years. Am I on the right track or am I going to be working until I'm 70?
I've got £20k in an adventurous plan, and I'm paying in over £1k each month by salary sacrifice.
What's confusing me is that I'm finding it hard to understand what my projected retirement figures will be. I know there are many assumptions to take into account, and absolutely everything is a best guess. Still, the figures I am getting are widely different (from £12k PA to £40k PA).
In any case, Nutmegs calculator lets me input my own figures, and assuming 8% growth the figures look healthy?
It's probably worth mentioning that I'd be happy with an annual income of £20k, but I have no idea what that will be in 25 years. Am I on the right track or am I going to be working until I'm 70?
Condi said:
8% is a very punchy long term RoR, especially as you'll want to de-risk as you get towards retirement.
That's a good point, thank you.RichTT said:
Are you planning on living to 108 years old? A million pounds will last you 50 years at 20k a year, or 33 years at 30k a year. Of course that's assuming there's no growth on your portfolio. Also you're not including your state pension.
That's kind of my point, I don't know what figures to 'believe' as every website gives different results. I have no interest in working to the state pension age, so while it will be nice to have when it gets paid, I'm not relying on it.
3xAAA said:
That's kind of my point, I don't know what figures to 'believe' as every website gives different results.
I have no interest in working to the state pension age, so while it will be nice to have when it gets paid, I'm not relying on it.
You have £20K and you want to work for 25 years and from the sounds of it (no mention of other savings?) then be able to retire?I have no interest in working to the state pension age, so while it will be nice to have when it gets paid, I'm not relying on it.
So it comes down to how much will be in the pot by 58 and whether that's enough to then draw from whilst also hopefully having it continue to grow v working longer.
A compound interest calculator might be useful.
https://monevator.com/compound-interest-calculator...
soad said:
55palfers said:
Plus, the older you get, the less money you spend.
Not necessarily. 
I can't see how I'll need that much cash when I'm older. My mortgage is almost gone, I'll be too old to do any of my current hobbies or sports, I won't be buying expensive designer clothing, I won't be chasing skirt

I'll just be bumbling along in life with a few nice holidays a year.
Having said that, I don't want to be caught short. The idea of working into my 60s makes me want to slit my wrists
3xAAA said:
Condi said:
8% is a very punchy long term RoR, especially as you'll want to de-risk as you get towards retirement.
That's a good point, thank you.Have a look at this site which has a number of useful spreadsheets you can download:
https://www.vertex42.com/
https://www.vertex42.com/Calculators/retirement-ca...
Although they are in dollars & refer to some American concepts it's not difficult to manipulate the sheet to be more UK biased. This is a rough example of what your numbers might look like, although with a 6% return after charges:
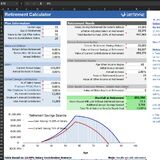
Note that this is a bit crude & if you want a better indication then either speak to an IFA who has access to one of the more sophisticated packages or have a look at the IM sticky thread at the top of this forum & consider talikng to them.
Mr Pointy said:
3xAAA said:
Condi said:
8% is a very punchy long term RoR, especially as you'll want to de-risk as you get towards retirement.
That's a good point, thank you.Have a look at this site which has a number of useful spreadsheets you can download:
https://www.vertex42.com/
https://www.vertex42.com/Calculators/retirement-ca...
Although they are in dollars & refer to some American concepts it's not difficult to manipulate the sheet to be more UK biased. This is a rough example of what your numbers might look like, although with a 6% return after charges:
Note that this is a bit crude & if you want a better indication then either speak to an IFA who has access to one of the more sophisticated packages or have a look at the IM sticky thread at the top of this forum & consider talikng to them.
Just to add, I did include my pension providers 0.4% charge in the Nutmeg example.
Two things:
1) You'll be more active in your 60s than you think you will. I am, I still do most of the things I did in my 40s and do them more often as I have more time. My BiL still rides his mountain bike in Utah and goes heli-skiing in Alaska and he's in his 70s.
2) Assuming the rules don't change, you won't be paying National Insurance once you retire nor (presumably) paying into a pension. That is quite a large percentage of your current income that you won't need post retirement.
1) You'll be more active in your 60s than you think you will. I am, I still do most of the things I did in my 40s and do them more often as I have more time. My BiL still rides his mountain bike in Utah and goes heli-skiing in Alaska and he's in his 70s.
2) Assuming the rules don't change, you won't be paying National Insurance once you retire nor (presumably) paying into a pension. That is quite a large percentage of your current income that you won't need post retirement.
I think 8% is fine. That's about what the average stock market return has been.
There are plenty of funds out there that have been averaging twice that. Yes there is more risk, but you are a long way off retirement age.
Paying 1k a Month is going to make a really positive differ- plenty of time for compound interest to work its magic!
There are plenty of funds out there that have been averaging twice that. Yes there is more risk, but you are a long way off retirement age.
Paying 1k a Month is going to make a really positive differ- plenty of time for compound interest to work its magic!
3xAAA said:
It's going to vary by person to person, but I agree with Palfers.
I can't see how I'll need that much cash when I'm older. My mortgage is almost gone, I'll be too old to do any of my current hobbies or sports, I won't be buying expensive designer clothing, I won't be chasing skirt
I'll just be bumbling along in life with a few nice holidays a year.
Having said that, I don't want to be caught short. The idea of working into my 60s makes me want to slit my wrists
What happens when you can't look after yourself & have to move into a nursing home at £1500 a week? Or need a hip replacement for £10k to avoid a two year wait in increasing agony for a NHS slot?I can't see how I'll need that much cash when I'm older. My mortgage is almost gone, I'll be too old to do any of my current hobbies or sports, I won't be buying expensive designer clothing, I won't be chasing skirt
I'll just be bumbling along in life with a few nice holidays a year.
Having said that, I don't want to be caught short. The idea of working into my 60s makes me want to slit my wrists
Trust me, as you get older you realise how much you are going to need money if you don't want life to be a misery. You're possibly extrapolating what life is like at 70 from how it is now; it isn't like that at all.
On the bright sdie you realise you need to start saving which is a good first step.
3xAAA said:
I'll be too old to do any of my current hobbies or sports, I won't be buying expensive designer clothing, I won't be chasing skirt
I'll just be bumbling along in life with a few nice holidays a year.
:
So before you get there you want to live like this?......I'll just be bumbling along in life with a few nice holidays a year.
:
https://depositphotos.com/vector-images/donkey-car...
f
 k me. If that's the life plan you'd be better investing in a stout rope and locating a strong tree.
Pit Pony said:
RichTT said:
Also you're not including your state pension.
Which is 134 quid a week.. for a couple that is £14,000 a year..Now if you own your house, get a free bus pass, and don't have expensive tastes, that's enough to cover all your needs.
Fast and Spurious said:
Pit Pony said:
RichTT said:
Also you're not including your state pension.
Which is 134 quid a week.. for a couple that is £14,000 a year..Now if you own your house, get a free bus pass, and don't have expensive tastes, that's enough to cover all your needs.
Fast and Spurious said:
Someone will soon be along to say that you need at least £50k p.a. or you are a peasant living on beans.
This opened my eyes a little How much would you need to be able to retire right now?
Pit Pony said:
Which is 134 quid a week.. for a couple that is £14,000 a year..
Now if you own your house, get a free bus pass, and don't have expensive tastes, that's enough to cover all your needs.
It's actually £175.20p per week (and goes up a tiny bit every year)Now if you own your house, get a free bus pass, and don't have expensive tastes, that's enough to cover all your needs.
Edited by Groat on Saturday 30th January 16:33
Gassing Station | Finance | Top of Page | What's New | My Stuff