
Churchill's car insurance quote...
Discussion


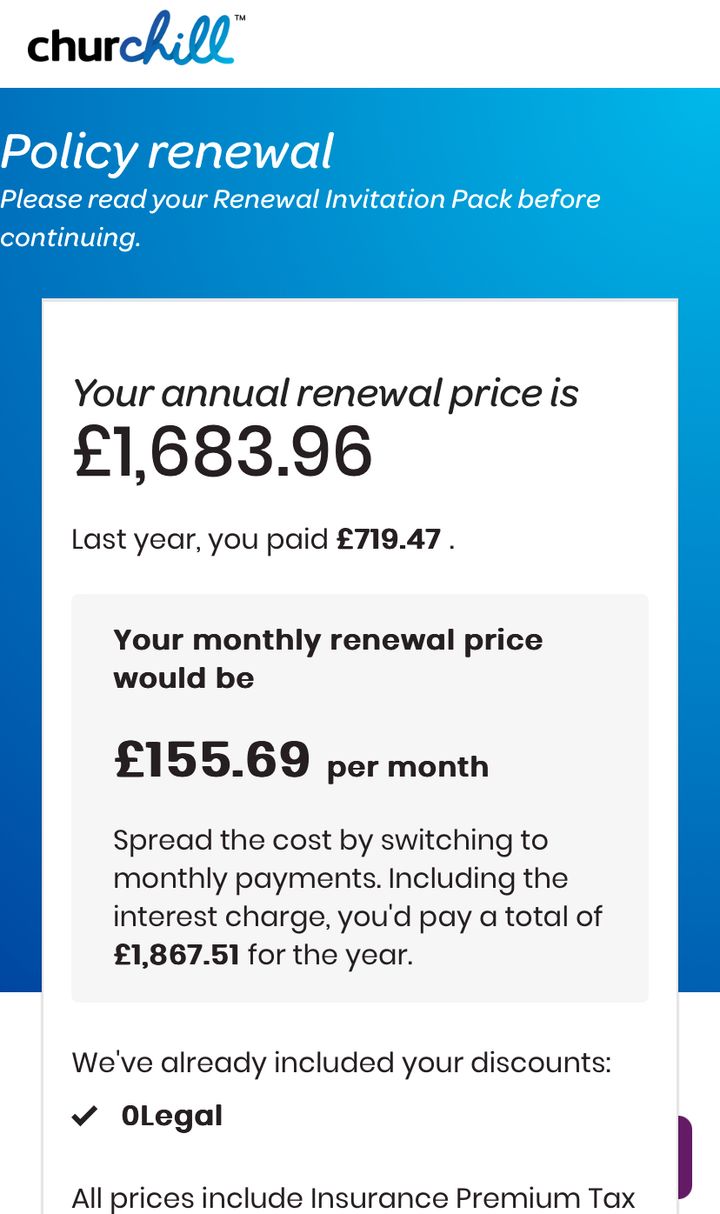
Insurance due to renew later this month. No changes to any detail, Churchill sent me this....
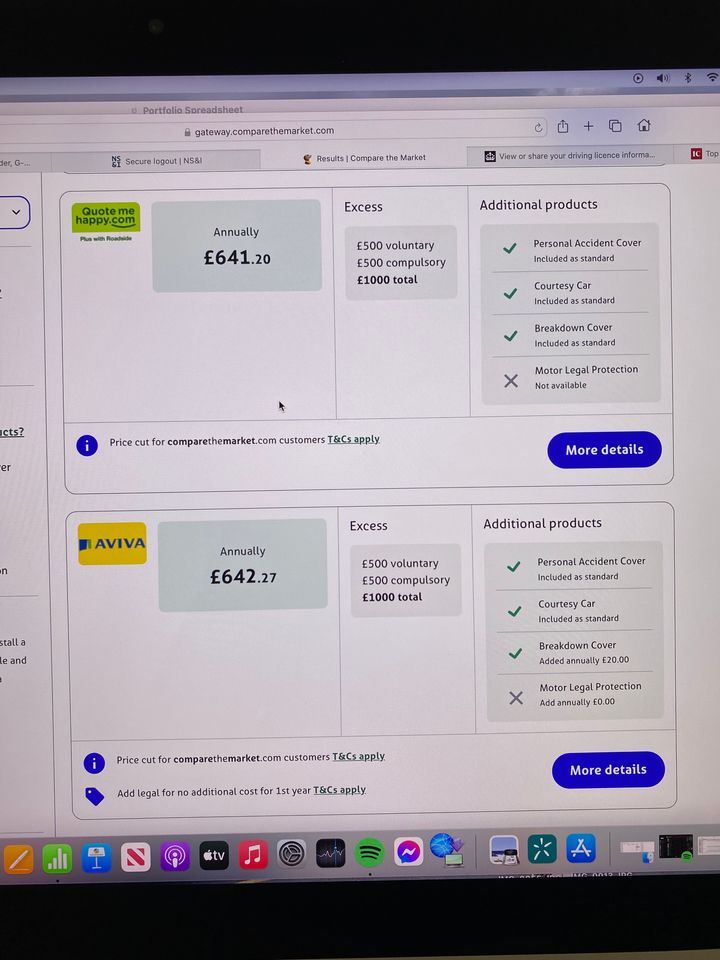
Had a quick look on Comparethemarket, exactly same details, and here's an extract of the quotes (these aren't the cheapest btw - that was £616, just like for like deets and couple of known brands)....
Called Churchill to see if their price is an error. It's not! This is for a 4 year old Lexus RX450, I'm 61, retired, and have full (whatever, 9yr+) ncd eligibility and full, clean licence with no points history whatsoever.
I'm obvs not going to renew with them, and I'm not going to argue with them (it's their price and assessment of risk/algorythm), but f k me, that's ridiculous.
Had a quick look on Comparethemarket, exactly same details, and here's an extract of the quotes (these aren't the cheapest btw - that was £616, just like for like deets and couple of known brands)....
Called Churchill to see if their price is an error. It's not! This is for a 4 year old Lexus RX450, I'm 61, retired, and have full (whatever, 9yr+) ncd eligibility and full, clean licence with no points history whatsoever.
I'm obvs not going to renew with them, and I'm not going to argue with them (it's their price and assessment of risk/algorythm), but f
k me, that's ridiculous.I've noticed that quite a few Insurers now allow you to click and cancel online, rather than go through their retentions department and the "requote" bull.
I was with Tesco (BISL) who wanted £660 in December for renewal. So because I'm a tt, I went on the Tesco website to get a new quote... £400. So I cancelled with Tesco and took out a new policy with them. All these FCA rules on equal
pricing for new and existing customers - Pah!
I was with Tesco (BISL) who wanted £660 in December for renewal. So because I'm a t
t, I went on the Tesco website to get a new quote... £400. So I cancelled with Tesco and took out a new policy with them. All these FCA rules on equal pricing for new and existing customers - Pah!
Not uncommon.
Maybe their terms have changed, maybe you've moved up an age bracket or maybe they don't want your business this year or maybe are hoping you'll just blindly renew.
It's no big deal, shop around... as you've sussed, you'll get cover cheaper elsewhere. Customer loyalty is no longer rewarded so it pays to shop around at renewal time.
That said, just renewed my wife with Tesco... £9 increase over last year taking it to £197 so it's not worth the hassle of changing. Win some, lose some.
Maybe their terms have changed, maybe you've moved up an age bracket or maybe they don't want your business this year or maybe are hoping you'll just blindly renew.
It's no big deal, shop around... as you've sussed, you'll get cover cheaper elsewhere. Customer loyalty is no longer rewarded so it pays to shop around at renewal time.
That said, just renewed my wife with Tesco... £9 increase over last year taking it to £197 so it's not worth the hassle of changing. Win some, lose some.
Obviously time for the annual game-playing exercise, then.
We had a multicar policy last year at a decent prices. Silly price this year. Searched around and got:
Me: for a BMW 335d ‘66 plate £323 with the AA
Wife: for a Fabia ‘13 plate £178 with the RAC
(Yes, I know they are underwritten by another firm)
Excellent driving histories, 76/73 years old respectively.
IAM membership appears to make no difference, just driving history/experience.
The more people accept these prices, the more they stay high.
All the usual advice. Make sure that the cover is not over what you need, but is adequate.
We had a multicar policy last year at a decent prices. Silly price this year. Searched around and got:
Me: for a BMW 335d ‘66 plate £323 with the AA
Wife: for a Fabia ‘13 plate £178 with the RAC
(Yes, I know they are underwritten by another firm)
Excellent driving histories, 76/73 years old respectively.
IAM membership appears to make no difference, just driving history/experience.
The more people accept these prices, the more they stay high.
All the usual advice. Make sure that the cover is not over what you need, but is adequate.
vikingaero said:
I've noticed that quite a few Insurers now allow you to click and cancel online, rather than go through their retentions department and the "requote" bull.
I was with Tesco (BISL) who wanted £660 in December for renewal. So because I'm a tt, I went on the Tesco website to get a new quote... £400. So I cancelled with Tesco and took out a new policy with them. All these FCA rules on equal
pricing for new and existing customers - Pah!
They’ll say it’s a different policy. Just watch there isn’t something that you rely on missing from the new policy - dropping DOC off is a favourite.I was with Tesco (BISL) who wanted £660 in December for renewal. So because I'm a t
t, I went on the Tesco website to get a new quote... £400. So I cancelled with Tesco and took out a new policy with them. All these FCA rules on equal pricing for new and existing customers - Pah!
I suspect they've loaded the premium because Lexus RX's are very easy to steal
https://www.lexusownersclub.co.uk/forum/topic/1450...
https://www.lexusownersclub.co.uk/forum/topic/1450...
As has been stated already its not a big issue getting cheaper elsewhere but"optically" you can see why motor Insurers aren't liked -with this type of doubling premium's behaviour - if they had written and said " sorry but due to a change in underwriting strategy we cannot offer terms on your car any more " you might have a tiny bit more respect -very tiny though.
I know you said you didn't want to argue with them but once you have found that much cheaper alternative if you can bear to ring them back and say you are leaving them but will give them one chance to reduce their quote it might be interesting to see what they say/do ?
I know you said you didn't want to argue with them but once you have found that much cheaper alternative if you can bear to ring them back and say you are leaving them but will give them one chance to reduce their quote it might be interesting to see what they say/do ?
Lotobear said:
Is this massive hike in premiums the insurance market levelling out the disproportionately increased risk of insuring EV's I wonder?
Not if they have any underwriting sense...Unless they are already running a book of esoteric / specialised business they should be wanting to have a generic wide spread account of business.
Ending up getting rid of some "profitable" accounts from doubling premiums means in effect they will end up with being selected against with those that for whatever reason renew.
Quotes are driven by actuarial derived rating models with a large element of computer driven input so in effect no manual interpretation of how much to charge.
Got my renewals in via email this morning.
Both my wife and I are 53, semi rural Wiltshire, full NCD and no claims or convictions etc.
My car has gone up £2 from last year, my wife's £34.
A quick look on one the usual suspects has found a like for like policy for £139 less on her car and £55 less for mine.
It's a dance we play every year, I'll just swap them over instead of trying to get them closer with the present insurers..
Both my wife and I are 53, semi rural Wiltshire, full NCD and no claims or convictions etc.
My car has gone up £2 from last year, my wife's £34.
A quick look on one the usual suspects has found a like for like policy for £139 less on her car and £55 less for mine.
It's a dance we play every year, I'll just swap them over instead of trying to get them closer with the present insurers..
alscar said:
I know you said you didn't want to argue with them but once you have found that much cheaper alternative if you can bear to ring them back and say you are leaving them but will give them one chance to reduce their quote it might be interesting to see what they say/do ?
Not sure on that one... I sometimes view their renewal as their one chance and whilst yes, they're in the business of making money, if they actually cared about your as a loyal customer they may look at the premium, compare it and make contact to say "Sorry, it is increasing but we can do X, Y or Z" but that's not how the vast majority of the industry works. I also work on the basis that cheapest is not always best either. Saving £50 a year might be a big deal but I'd sooner pay that and have a good insurer than save it and have one who is useless if / when a claim happens. Freakuk said:
Have to do this most years, I think insurance companies take a hit in the first year to lure you in and then just expect a % will just renew without looking for another quote.
Admiral seem to be one of the ones that double quotes for year 2 and beyond.
^This^Admiral seem to be one of the ones that double quotes for year 2 and beyond.
Its pretty much the annual game of "Insert insurance comparison site here" vs your current insurer game.
The 7 minutes to check against other sites / insurers is well worth the £££'s saved.
We all know that insurers make their cash from the auto renew / folk that shrug and accept it.
Davie said:
alscar said:
I know you said you didn't want to argue with them but once you have found that much cheaper alternative if you can bear to ring them back and say you are leaving them but will give them one chance to reduce their quote it might be interesting to see what they say/do ?
Not sure on that one... I sometimes view their renewal as their one chance and whilst yes, they're in the business of making money, if they actually cared about your as a loyal customer they may look at the premium, compare it and make contact to say "Sorry, it is increasing but we can do X, Y or Z" but that's not how the vast majority of the industry works. I also work on the basis that cheapest is not always best either. Saving £50 a year might be a big deal but I'd sooner pay that and have a good insurer than save it and have one who is useless if / when a claim happens. I don't think customer loyalty is cared about by pretty much anyone these days ( unless you move to the more esoteric / HNW Insurers ) which becomes paradoxical when you consider they actively appear not to encourage it.
Quite agree about your cheapest comment too.
I'd add that's why I always use a broker to get my Insurance - let them do all the work as it won't cost you any more and they often have access to a different Insurer base normally appearing on a comparison site.
I do accept that my Insurance isn't cheap though.
quinny100 said:
I suspect they've loaded the premium because Lexus RX's are very easy to steal
https://www.lexusownersclub.co.uk/forum/topic/1450...
This.https://www.lexusownersclub.co.uk/forum/topic/1450...
Lexus are now offering canbus protection plates, a tracker and a geofence device free of charge.
Because they’ve been so easy to export I believe some insurers have seen their Lexus insurance profits go full Land Rover over the last couple of years - hence Churchill not wanting OPs business perhaps.
andy43 said:
quinny100 said:
I suspect they've loaded the premium because Lexus RX's are very easy to steal
https://www.lexusownersclub.co.uk/forum/topic/1450...
This.https://www.lexusownersclub.co.uk/forum/topic/1450...
Lexus are now offering canbus protection plates, a tracker and a geofence device free of charge.
Because they’ve been so easy to export I believe some insurers have seen their Lexus insurance profits go full Land Rover over the last couple of years - hence Churchill not wanting OPs business perhaps.
alscar said:
As has been stated already its not a big issue getting cheaper elsewhere but"optically" you can see why motor Insurers aren't liked -with this type of doubling premium's behaviour - if they had written and said " sorry but due to a change in underwriting strategy we cannot offer terms on your car any more " you might have a tiny bit more respect -very tiny though.
I know you said you didn't want to argue with them but once you have found that much cheaper alternative if you can bear to ring them back and say you are leaving them but will give them one chance to reduce their quote it might be interesting to see what they say/do ?
I did speak with them, just to check it wasn't a mistake. Told them the range of like for like quotes via compare the market, and their response was..."we don't seek to be the cheapest". Fair enough, but more than 2x last years premium and almost 3x similar policies elsewhere? As someone else suggested, maybe I'm in a diff category for their algorythms. Whatever...I'll just go elsewhere.I know you said you didn't want to argue with them but once you have found that much cheaper alternative if you can bear to ring them back and say you are leaving them but will give them one chance to reduce their quote it might be interesting to see what they say/do ?
Gassing Station | General Gassing | Top of Page | What's New | My Stuff