
£50K to invest property or stock & Shares??
Discussion


As the title suggests would like a general consensus on investing circa £50K would consider both long term and short term options. Need to investigate both the above options but was hoping some others may be able to shed some light on their own experiences or advise on which of the above is best (if either) If it was property is it best to buy two 1 bed places to rent or a 3 bed family house. Either way it would be local to me Fleet/Farnborough(3 bed semi approx £190,000 - £240,000). Stock market is a little more of an unknown but is it worth a serious look at this stage. BTW am not looking at making mega money over a short period would just feel more comfortable having my c£50K working better for me than sat in a savings account earning next to no interest.

swerni said:
ShadownINja said:
Property is a safer bet. With the stock market you could lose it all. At least you stand a chance of recuperating some of your investment.
lots of £50k houses where you live then?£250k flat £50k deposit that drops 30% then you're £25k in a hole.
Yes you could lose it all on the markets but only if the shares you invest in drop and you watch them go to zero without selling.
I would suggest speaking to a couple of IFA's instead of us numpties

swerni said:
ShadownINja said:
swerni said:
ShadownINja said:
Property is a safer bet. With the stock market you could lose it all. At least you stand a chance of recuperating some of your investment.
lots of £50k houses where you live then?£250k flat £50k deposit that drops 30% then you're £25k in a hole.
Yes you could lose it all on the markets but only if the shares you invest in drop and you watch them go to zero without selling.
I would suggest speaking to a couple of IFA's instead of us numpties
With shares the worse that could happen is you could lose £50k.
With a house you could lose far more
PS sod the IFAs. I don't think they expected their clients' pension funds to be up the creek right now.
Edited by ShadownINja on Thursday 11th June 18:44
Shares would let you diversify far more than property. Buy 25 shares in a broad range of sectors and let the dividends roll in over the long term. You could jump out of individual positions if you have concerns over the company involved but generally the winners will slightly outweigh the losers in the long term unless the overall market is down.
I cant remember the exact theory but I think it was Markowitz who won a noble prize with his theory of once you have about 20 individual investments the firm specific risk is almost negligible and you are left only with overall market risk?
I cant remember the exact theory but I think it was Markowitz who won a noble prize with his theory of once you have about 20 individual investments the firm specific risk is almost negligible and you are left only with overall market risk?
swerni said:
so if the £50k is just the deposit then the risk is clearly greater than with shares.
With shares the worse that could happen is you could lose £50k.
With a house you could lose far more
This is true. But so is the upside that you haven't even considered.With shares the worse that could happen is you could lose £50k.
With a house you could lose far more
Same example- your own property £250k, prices down 30%* total theoretical value £175, less than the mortgage, you lose 25k.
Which assumes you sell and hence crystalise the loss.
Alternatively, your own property £250k, prices UP 30%, total theoretical value £325. Your £50k now (if you choose to sell) up to £125k.
ROI 150%.
Alternatively you buy shares. £50k in, maximum theoretical loss, £50k.
Maximum theoretical gain? Unlimited. But how long are you going to be in to realise a 150% gain?
And don't forget, if the same property increases in value to £325k, the OP could potentially remortgage and release the original £50k s/he put in, either to simple mean s/he has none of his/ her own money in the property, or to spend on whatever else. Tax would of course be payable on the gain in price, but only when the property is sold.
Things are never quite as simple as this of course, but you've not stated why your example only has prices going one way. The * is to indicate that if property falls 30% from where it is today, my Gran will be on eBay as I will happily buy even more.
ETA: At no point am I saying that I know/ think/ believe that the property market will rise. To do that I'd have to have a crystal ball, in which case I'd have won the lottery many times, and would be sitting on my Super Yacht surrounded by Girls Aloud, not typing on Pistonheads!
Edited by DonkeyKong on Thursday 11th June 23:18
WRT the 20 stock portfolio idea, that's really for professionals who have an idea which stocks are going to make it, rather than a newbie picking completely random stocks, surely?
And even if they pick the right ones on average, there's the whole notion of managing a position so you get out at the right time. Warren Buffett has been doing it for years...
And even if they pick the right ones on average, there's the whole notion of managing a position so you get out at the right time. Warren Buffett has been doing it for years...
DonkeyKong said:
swerni said:
so if the £50k is just the deposit then the risk is clearly greater than with shares.
With shares the worse that could happen is you could lose £50k.
With a house you could lose far more
Alternatively, your own property £250k, prices UP 30%, total theoretical value £325. Your £50k now (if you choose to sell) up to £125k. With shares the worse that could happen is you could lose £50k.
With a house you could lose far more
I'm seriously worried for your gran...
Investment studies of portfilio managers show approx 90% of a portfolios returns are down to the target asset allocation, variations of returns in allocated portfolios are approx 40%, so it shows that getting the asset class right is more important than individual stock selection and this for people who are supposed to know what they are doing!
Risk is the far more important consideration in an investment than a return..so don't get too optimistic with your return projections.
Risk is the far more important consideration in an investment than a return..so don't get too optimistic with your return projections.
VX Foxy said:
Where have you been for the last 18mths?
Buying houses from people otherwise about to be repossessed at figures typically only just above any mortgage redemption figure, which (depending on how long someone has owned a property) can be very low in comparison to the (potential and theoretical) open market value. This is usually referred to as "BMV" purchasing. As I'm interested solely in long-term rentals and usually Houses of Multiple Occupation (where rooms are let on an individual basis) I've been having a whale of a time. I've bought properties for under £100k that 2 years ago I'd have been buying at 180+. The rental figures on these things stack up at 85% LTV assuming 7% interest rates at 180k. So believe me, they work VERY well at a ton or less.DonkeyKong said:
VX Foxy said:
Where have you been for the last 18mths?
Buying houses from people otherwise about to be repossessed at figures typically only just above any mortgage redemption figure, which (depending on how long someone has owned a property) can be very low in comparison to the (potential and theoretical) open market value. This is usually referred to as "BMV" purchasing. As I'm interested solely in long-term rentals and usually Houses of Multiple Occupation (where rooms are let on an individual basis) I've been having a whale of a time. I've bought properties for under £100k that 2 years ago I'd have been buying at 180+. The rental figures on these things stack up at 85% LTV assuming 7% interest rates at 180k. So believe me, they work VERY well at a ton or less.
I opened a Hargreaves Langsdown account - https://www.h-l.co.uk/ We drip feed money in each month and semi randomly invest in different funds & ftse 100 shares. 3 months in and we're about 5% up which is fluke of course. We're looking at it as a college fund so a 10-15 year timescale.
DonkeyKong said:
VX Foxy said:
Where have you been for the last 18mths?
Buying houses from people otherwise about to be repossessed at figures typically only just above any mortgage redemption figure, which (depending on how long someone has owned a property) can be very low in comparison to the (potential and theoretical) open market value. This is usually referred to as "BMV" purchasing. As I'm interested solely in long-term rentals and usually Houses of Multiple Occupation (where rooms are let on an individual basis) I've been having a whale of a time. I've bought properties for under £100k that 2 years ago I'd have been buying at 180+. The rental figures on these things stack up at 85% LTV assuming 7% interest rates at 180k. So believe me, they work VERY well at a ton or less.1975wmj said:
As the title suggests would like a general consensus on investing circa £50K would consider both long term and short term options. Need to investigate both the above options but was hoping some others may be able to shed some light on their own experiences or advise on which of the above is best (if either) If it was property is it best to buy two 1 bed places to rent or a 3 bed family house. Either way it would be local to me Fleet/Farnborough(3 bed semi approx £190,000 - £240,000). Stock market is a little more of an unknown but is it worth a serious look at this stage. BTW am not looking at making mega money over a short period would just feel more comfortable having my c£50K working better for me than sat in a savings account earning next to no interest.
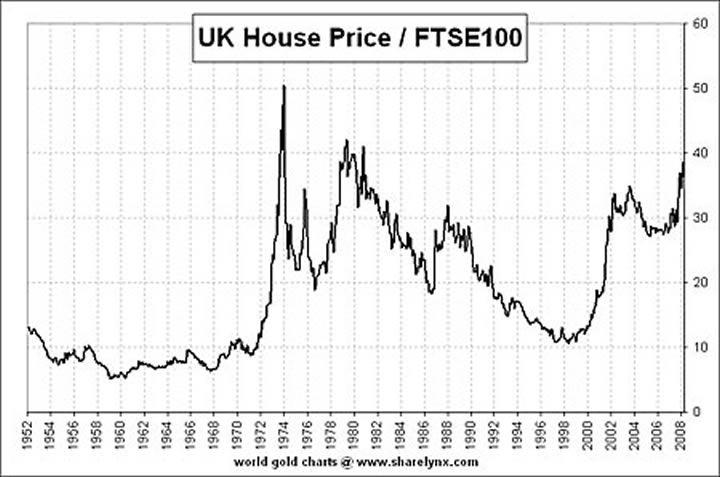
Why can't you get 4% on a savings account?Property vs. FTSE
DonkeyKong said:
swerni said:
so if the £50k is just the deposit then the risk is clearly greater than with shares.
With shares the worse that could happen is you could lose £50k.
With a house you could lose far more
This is true. But so is the upside that you haven't even considered.With shares the worse that could happen is you could lose £50k.
With a house you could lose far more
Same example- your own property £250k, prices down 30%* total theoretical value £175, less than the mortgage, you lose 25k.
Which assumes you sell and hence crystalise the loss.
Alternatively, your own property £250k, prices UP 30%, total theoretical value £325. Your £50k now (if you choose to sell) up to £125k.
ROI 150%.
Alternatively you buy shares. £50k in, maximum theoretical loss, £50k.
Maximum theoretical gain? Unlimited. But how long are you going to be in to realise a 150% gain?
And don't forget, if the same property increases in value to £325k, the OP could potentially remortgage and release the original £50k s/he put in, either to simple mean s/he has none of his/ her own money in the property, or to spend on whatever else. Tax would of course be payable on the gain in price, but only when the property is sold.
Things are never quite as simple as this of course, but you've not stated why your example only has prices going one way. The * is to indicate that if property falls 30% from where it is today, my Gran will be on eBay as I will happily buy even more.
ETA: At no point am I saying that I know/ think/ believe that the property market will rise. To do that I'd have to have a crystal ball, in which case I'd have won the lottery many times, and would be sitting on my Super Yacht surrounded by Girls Aloud, not typing on Pistonheads!
Edited by DonkeyKong on Thursday 11th June 23:18
Gassing Station | Business | Top of Page | What's New | My Stuff